
Benefits of Public Transportation (and What It Means for Your Car Insurance)
The benefits of public transportation, plus how commuters can save on car insurance.
The benefits of public transportation, plus how commuters can save on car insurance.
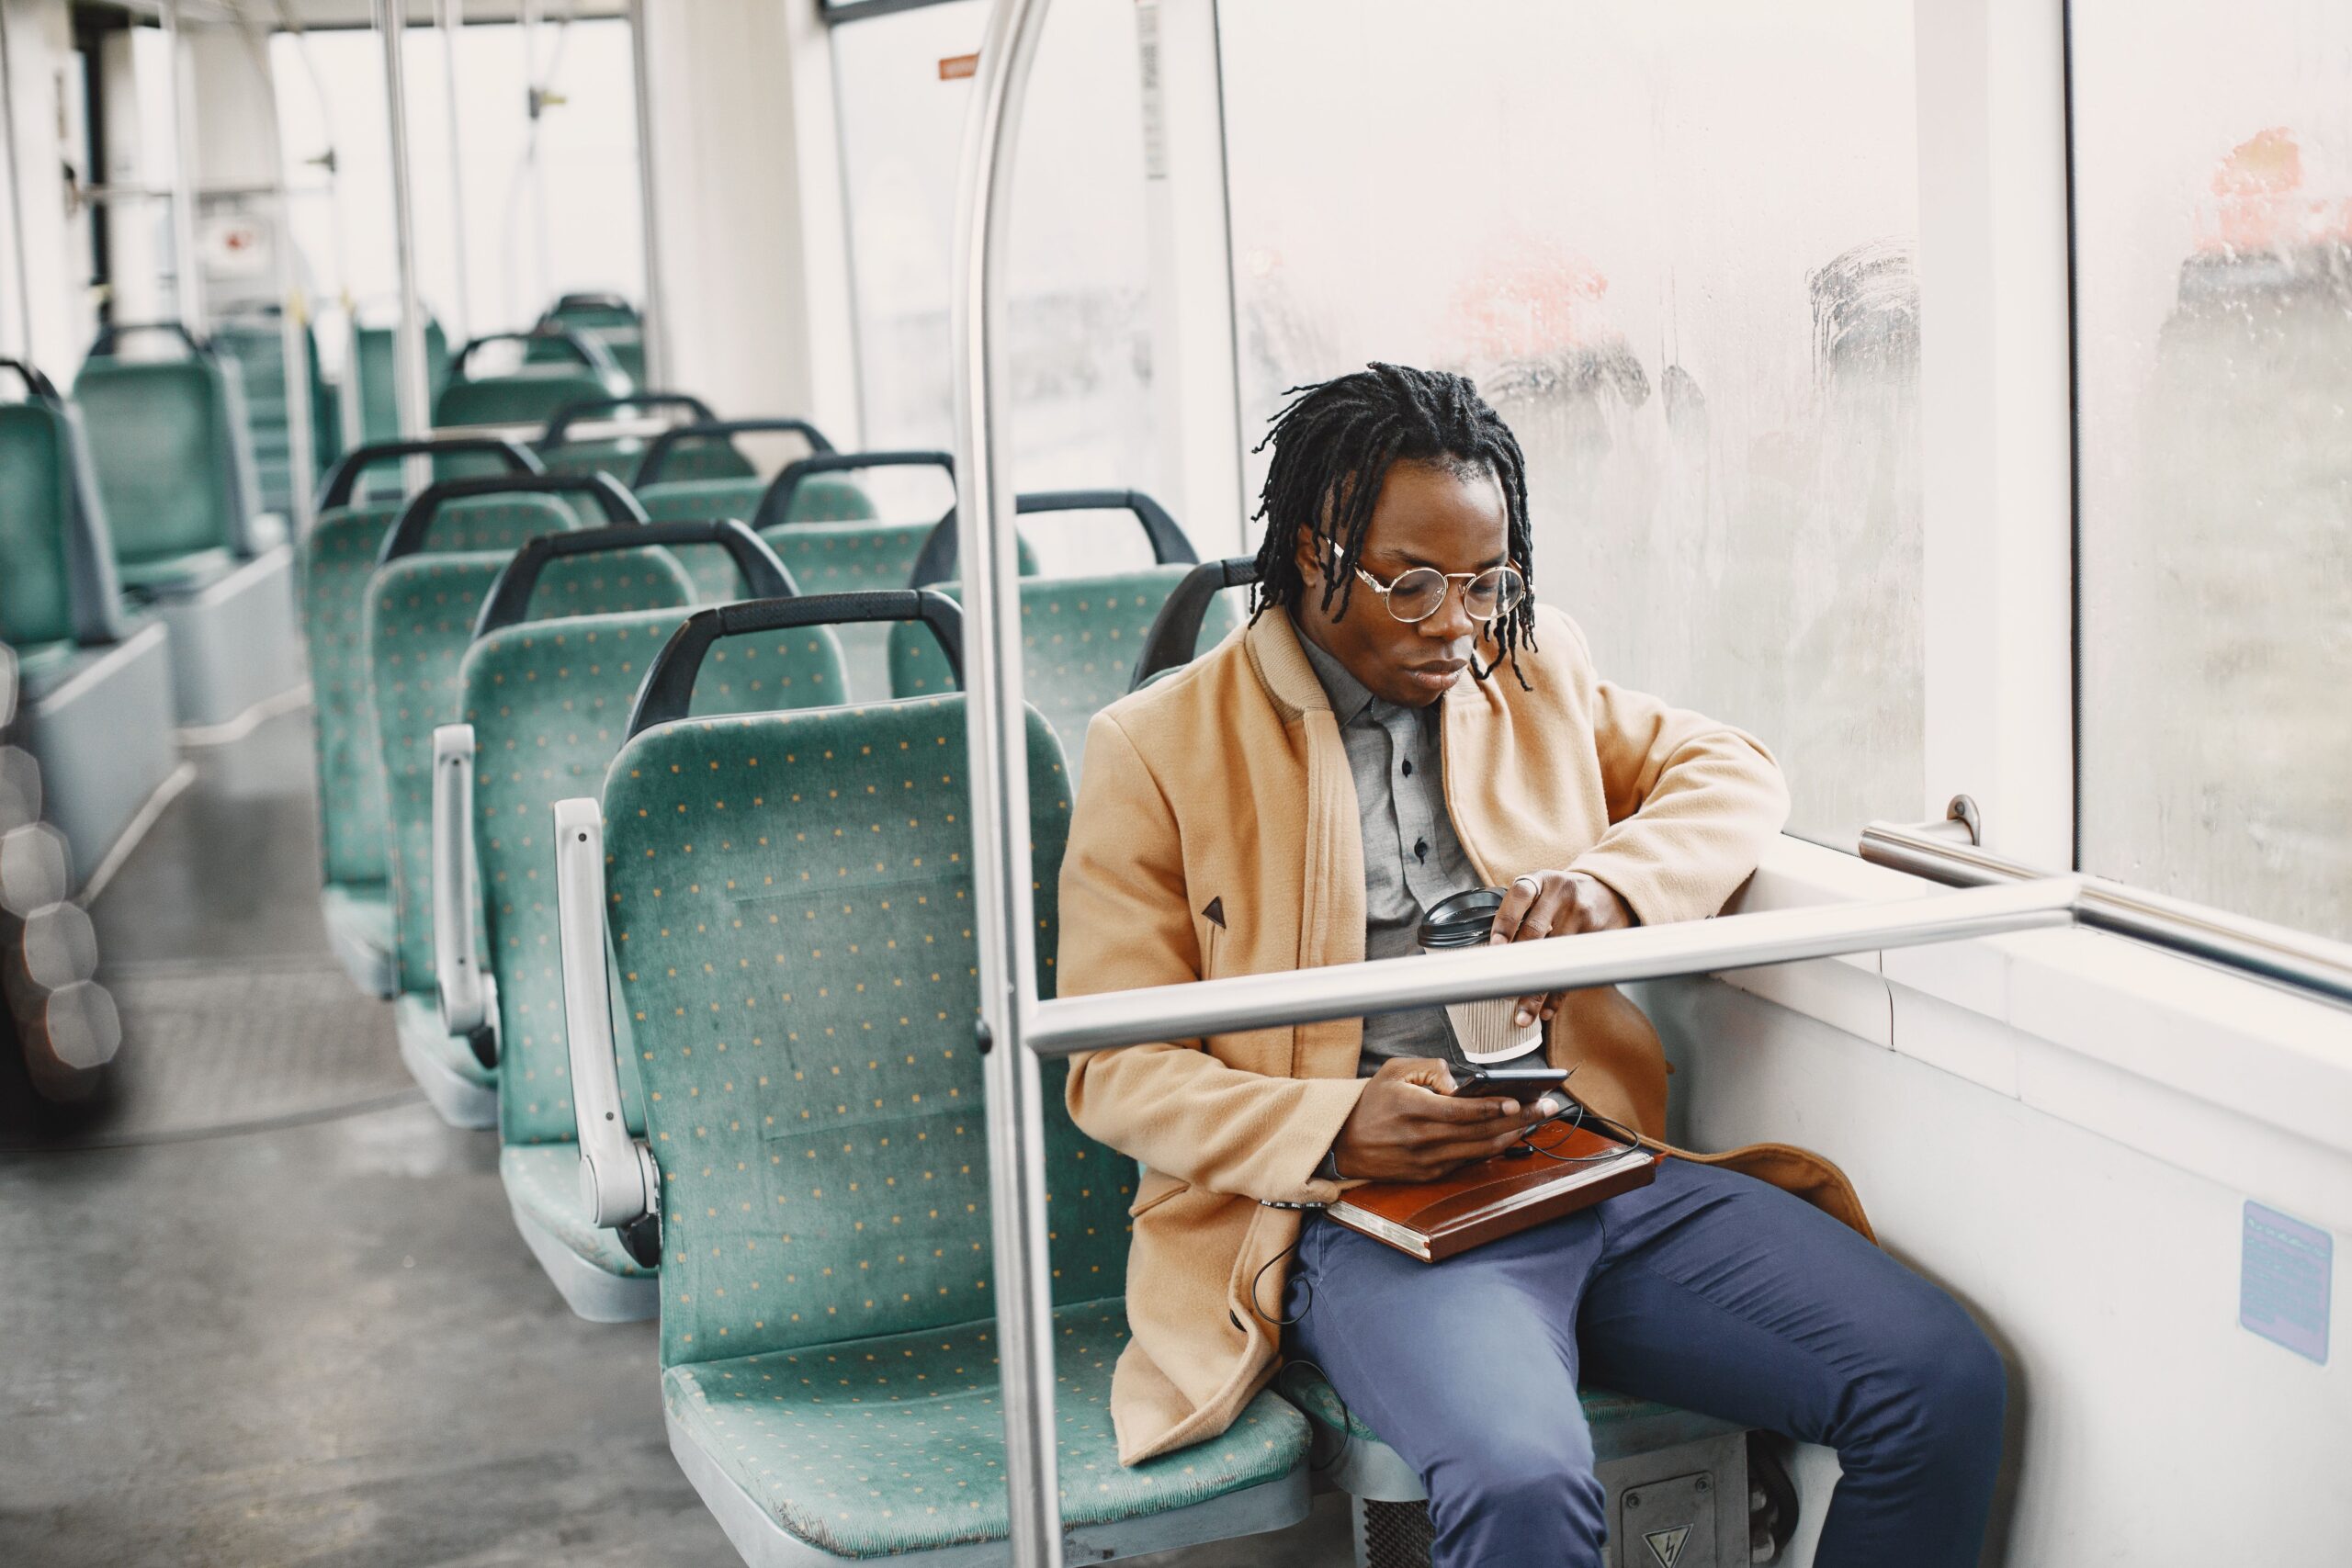
If you’ve been taking the bus or train to work and wondering whether it’s worth it, it almost certainly is. Less traffic, real money saved, and a commute you can actually use for something. And here’s the part most articles miss: driving less should mean paying less for car insurance.
Here’s what you need to know.
 TL;DR
The average person who switches from driving alone to using public transit can save more than $13,000 a year. That figure accounts for fuel, maintenance, parking, and car payments.
Here’s where those savings actually come from:
The benefits extend beyond individual savings too. Cities with strong transit systems attract businesses, reduce road infrastructure costs, and keep more money circulating locally.
The environmental benefits of public transportation are significant and measurable. US public transit systems collectively reduce carbon emissions by an estimated 37 million metric tons every year. To put that in perspective, that’s roughly equivalent to the entire carbon output of several mid-sized countries.
The logic is simple: a single bus or train can move dozens or hundreds of people using far less energy per passenger than individual cars. When you reduce driving by switching to transit, you’re directly cutting your personal carbon footprint, often dramatically.
Beyond CO2, public transit also reduces:
If reducing your carbon footprint is a priority, swapping even a few driving days a week for transit makes a real dent.
Strong public transit connects people to jobs, healthcare, schools, and services — regardless of whether they own a car. Transit-accessible neighborhoods tend to have higher property values, lower unemployment rates, and stronger local business activity.
For people who can’t afford a car, or who can’t drive due to age or disability, reliable public transit isn’t a convenience. It’s a lifeline.
Public transit isn’t a perfect replacement for driving everywhere. Here’s an honest look at where each one makes sense:
| Situation | Public transit | Driving |
|---|---|---|
| Urban core with frequent service | Strong fit | Often unnecessary |
| Suburban commuter corridor | Good fit | Higher cost, more stress |
| Rural or low-service area | Limited options | Usually necessary |
| Trips with multiple stops | Less practical | Better fit |
| Expensive or scarce parking | Clear advantage | Adds up fast |
| Heavy cargo or errands | Not ideal | Better fit |
For many people, the goal isn’t to eliminate the car, it’s to use it less. Transit for the commute, car for everything else. That hybrid approach is exactly the kind of low-mileage driving pattern that should be reflected in what you pay for car insurance.
Here’s the part that almost no one talks about: if you start commuting by transit and your annual mileage drops significantly, your car insurance situation changes, and you should update it accordingly.
Most insurers ask how you use your car: for commuting, for business, or for pleasure use only. If you’ve switched to transit for your daily commute and only drive on weekends or for errands, your car now qualifies for pleasure use car insurance. That classification typically comes with a lower rate, since pleasure-use drivers tend to log fewer miles and face less accident exposure during peak traffic hours.
Insurers use annual mileage as a key pricing factor. If you were previously driving 15,000 miles a year and you’re now driving 5,000, that’s a meaningful shift. Updating your mileage estimate with your insurer can lower your premium, and with some carriers, the difference is significant. This is one of the most overlooked car insurance savings moves for transit users.
Pay-per-mile insurance is built for exactly this situation. You pay a base rate plus a small amount for each mile you actually drive. For someone who commutes by train or bus and only uses their car occasionally, this can mean dramatically lower premiums compared to a standard policy priced for average mileage.
At Lemonade, we factor in how you actually use your car. If you’re a transit-first household keeping a car for occasional use, it’s worth exploring whether your current coverage still fits. A quick check on your annual mileage and use classification could mean real savings, which is a pretty good return on a five-minute conversation.
The benefits of using public transportation are real, and they compound. You spend less on your commute, reduce your environmental impact, move more, stress less, and free up time you used to spend in traffic. If that shift also means you’re driving a lot less, your car insurance should reflect the change.
Check whether your vehicle is still classified as a commuter car, update your mileage estimate, and look into whether pay-per-mile coverage makes sense for how you actually drive now. Small adjustments like these can add up to hundreds of dollars a year in savings, on top of everything transit is already saving you.
Possibly, in two main ways: reclassifying your car from commute use to pleasure use, and reporting lower annual mileage can potentially reduce your premium. Pay-per-mile insurance is also worth exploring if you’re only driving occasionally.
Pleasure use means your car isn’t used for a daily commute. It typically signals fewer miles and less peak-hour driving, which often translates to a lower insurance rate.
That’s a fair concern, and it depends heavily on where you live. In cities with frequent, well-maintained service, transit is a genuinely viable daily option. In others, it works better as a supplement — taking the train on good days and driving when you need flexibility. Even partial transit use can lower your annual mileage enough to affect your car insurance rate, so it doesn’t have to be all-or-nothing to be worth it.
Absolutely. Many transit users keep a car for trips that don’t work well on transit, like weekend errands or travel. Driving less frequently can actually save money on insurance, especially with pay-per-mile coverage designed for low-mileage drivers.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of the policies issued, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage may not be available in all states. Please note that statements about coverages, policy management, claims processes, Giveback, and customer support apply to policies underwritten by Lemonade Insurance Company or Metromile Insurance Company, a Lemonade company, sold by Lemonade Insurance Agency, LLC. The statements do not apply to policies underwritten by other carriers.
Please note: Lemonade articles and other editorial content are meant for educational purposes only, and should not be relied upon instead of professional legal, insurance or financial advice. The content of these educational articles does not alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. While we regularly review previously published content to ensure it is accurate and up-to-date, there may be instances in which legal conditions or policy details have changed since publication. Any hypothetical examples used in Lemonade editorial content are purely expositional. Hypothetical examples do not alter or bind Lemonade to any application of your insurance policy to the particular facts and circumstances of any actual claim.